Money & Personal Finance
Reading Your Salary Slip in India: PF, ESI, TDS, and Deductions Explained in Plain Words
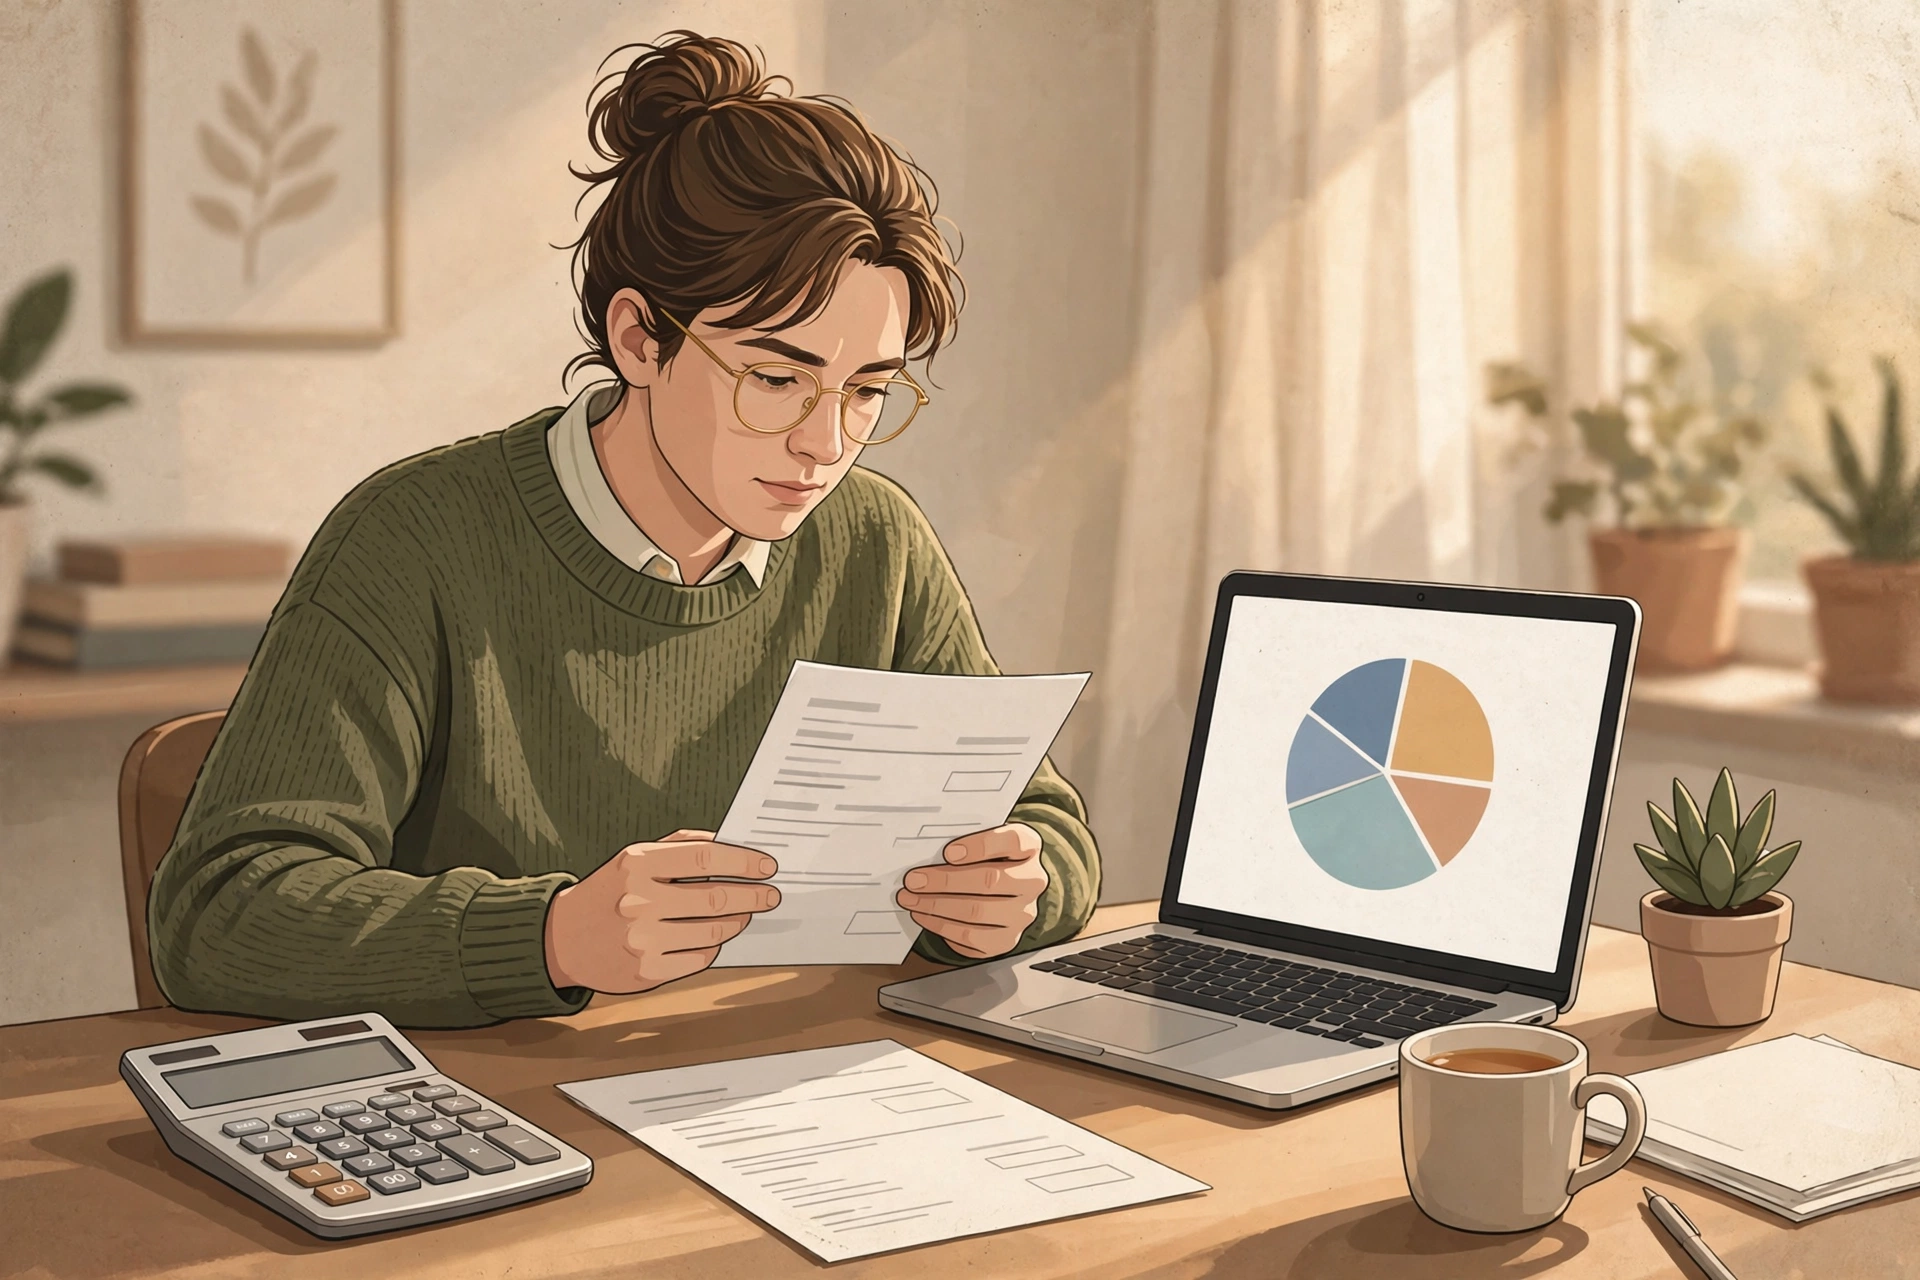
<p>Most people glance at the final credited amount on their salary slip and ignore the rest. That habit costs money, because the middle of the slip — earnings, deductions, and statutory contributions — is where errors hide. This guide explains each common line in plain words, shows what to check every month, and explains how to raise a problem with HR or payroll without creating a conflict. It uses general explanations only; your company's exact labels and rules may differ, so compare this guide with your own slip and your employment terms.</p><h2>Earnings: what you are paid before deductions</h2><p>The earnings section usually starts with basic salary, which is the core fixed component of your pay. On top of it you may see house rent allowance, which is meant to support housing costs and has specific tax treatment, and special allowance or other allowances that cover general expenses. Some slips also show overtime, incentives, bonuses, or reimbursements, which may appear only in certain months. Add these lines together to get your gross salary for the month. If an allowance suddenly disappears or a bonus appears without explanation, note it immediately, because it is easier to query in the same month than after several pay cycles. Keep your offer letter or appointment letter handy, since it defines which components were promised and how they are structured.</p><h2>Provident Fund: your long-term savings line</h2><p>Provident Fund, usually shown as PF or EPF, is a retirement savings contribution. In a typical setup, a part of your salary is deducted as your contribution, and your employer adds a matching contribution, subject to the rules that apply to your organisation and salary level. The money is held in a government-managed retirement account and earns interest as per the applicable rules. Check three things every month: that your PF deduction appears, that it matches the expected amount based on your basic salary, and that the employer's contribution is also shown where applicable. If you change jobs, do not withdraw the PF casually without understanding the tax and long-term consequences; transferring it to your new employer is often the better option. You can also check your PF balance through the official portal using your Universal Account Number.</p><h2>ESI and other social security deductions</h2><p>Employees' State Insurance, shown as ESI, applies to eligible employees in covered establishments and provides medical and related benefits. Both employee and employer contributions are usually shown, and eligibility depends on salary thresholds and establishment coverage, which change from time to time. If ESI appears on your slip, check that you know how to use the benefit — for example, which hospitals or dispensaries are covered — rather than treating it as just another deduction. Other lines you may see include professional tax, which is a state-level tax deducted where applicable, and labour welfare fund contributions in some states. These amounts are usually small, but they should still be consistent from month to month unless your salary or location has changed.</p><h2>Tax deducted at source: TDS explained simply</h2><p>Tax deducted at source, or TDS, is income tax that your employer deducts from your salary and deposits with the government on your behalf. It is not an extra charge on top of income tax; it is a way of paying income tax in advance, month by month. The amount depends on your estimated annual income, the tax regime you have chosen, and the declarations and proofs you have submitted, such as rent receipts or eligible investments. If your TDS suddenly jumps, it may be because a declaration was not submitted, a proof was rejected, or a bonus pushed your income into a higher calculation for that month. Review your tax declarations at the start of the financial year and after any major change, such as a salary revision, and keep copies of the proofs you submit.</p><h2>Other deductions: loans, advances, and recoveries</h2><p>Beyond statutory deductions, your slip may show deductions for salary advances, loans, canteen charges, uniform costs, or recovery of excess payments. These should always match an agreement or a communication you have received. A loan deduction should reduce month by month and end on the expected date; if it continues beyond that date, raise it promptly. Similarly, a recovery for leave or notice period should be explained in writing, not just appear as a number. If any deduction looks unfamiliar, do not ignore it because the amount is small — small recurring errors add up over a year. Make a habit of comparing this month's slip with last month's, line by line, which takes only a few minutes and catches most errors early.</p><h2>Your monthly five-minute check and how to raise errors</h2><p>Once a month, check five things: gross salary matches your expected components, PF and ESI appear correctly where applicable, TDS is in a plausible range, no unfamiliar deduction has appeared, and the net pay matches the amount credited to your bank account. If something is wrong, first gather evidence: the current slip, the previous slip, and your offer letter or relevant policy. Then write a short, polite email to HR or payroll describing the line, the amount, and the months affected, and ask for clarification or correction. Keep the email and any reply for your records. If the issue is not resolved, follow up once with the same thread and, if needed, escalate through your manager or the company's grievance process. Most payroll errors are data-entry mistakes and are corrected quickly when reported clearly and early.</p><h2>Frequently asked questions</h2><h3>Why is my take-home pay lower than my CTC?</h3><p>CTC includes employer contributions and benefits that are not paid to you in cash every month, while take-home pay is what remains after statutory and other deductions. The difference is normal, but the slip should make each part visible.</p><h3>What should I do if PF is not deducted?</h3><p>Check whether your organisation and salary level make PF applicable, then ask HR in writing. If it should apply and is missing, raise it promptly, because missing months can affect your retirement savings and records.</p><h3>Can TDS be refunded if too much is deducted?</h3><p>Excess TDS is generally adjusted when you file your income tax return, and any refund due is processed as per tax rules. Keep your salary slips and Form 16 to support your return.</p><h3>How long should I keep salary slips?</h3><p>Keep them at least until you have filed the relevant tax return and received your Form 16, and ideally longer for loan, visa, or employment verification purposes. Digital copies in a safe folder work well.</p><h2>Conclusion</h2><p>Your salary slip is not just a receipt; it is a monthly record of your earnings, savings, insurance, and tax. A five-minute check each month protects you from silent errors and helps you understand where your money actually goes. Learn the main lines, compare slips month to month, and raise problems early and politely with evidence. If anything on your slip conflicts with your employment terms, ask HR for a written explanation — that simple habit is the best protection your paycheque has.</p>
Share this article
About the Author
Related Articles
Money & Personal Finance
Starting Your First SIP in India: How Much to Invest, Which Fund to Pick, and Mistakes to Avoid
Creator
Money & Personal Finance
How to Check Your CIBIL Score for Free and Fix Common Errors in Your Credit Report
Creator
Money & Personal Finance
How to Choose a Family Health Insurance Policy in India: Sum Insured, Waiting Periods, and Claim Mistakes
Creator
Money & Personal Finance
First-Time Home Loan in India: Eligibility, Documents, and Mistakes That Delay Approval
Creator